Rechercher dans ce blog

Saturday, October 31, 2020

DPS releases names of victims killed in Tech Cafe crash - KLBK | KAMC | EverythingLubbock.com

takanadalagi.blogspot.com

[unable to retrieve full-text content]

DPS releases names of victims killed in Tech Cafe crash  KLBK | KAMC | EverythingLubbock.com

"cafe" - Google News
November 01, 2020 at 04:06AM
https://ift.tt/3oHSf2d

DPS releases names of victims killed in Tech Cafe crash - KLBK | KAMC | EverythingLubbock.com
"cafe" - Google News
https://ift.tt/2FkbMR3
https://ift.tt/3c4yPxW

Roz’s Cafe shows appreciation to poll workers by giving free lunch - WTVM

takanadalagi.blogspot.com

[unable to retrieve full-text content]

Roz’s Cafe shows appreciation to poll workers by giving free lunch  WTVM

"cafe" - Google News
November 01, 2020 at 03:40AM
https://ift.tt/2HLWXLr

Roz’s Cafe shows appreciation to poll workers by giving free lunch - WTVM
"cafe" - Google News
https://ift.tt/2FkbMR3
https://ift.tt/3c4yPxW

Here’s where the economy stands as the U.S. chooses between Trump and Biden - MarketWatch

2 killed, 5 injured when pickup crashes into Tech Cafe in South Lubbock - LubbockOnline.com

takanadalagi.blogspot.com

[unable to retrieve full-text content]

2 killed, 5 injured when pickup crashes into Tech Cafe in South Lubbock  LubbockOnline.com

"cafe" - Google News
October 31, 2020 at 11:49PM
https://ift.tt/37YheZf

2 killed, 5 injured when pickup crashes into Tech Cafe in South Lubbock - LubbockOnline.com
"cafe" - Google News
https://ift.tt/2FkbMR3
https://ift.tt/3c4yPxW

Genetic testing can assess your risk of getting cancer. Here are the costs involved - CNBC

Tara Kirk, pictured with her husband, found out she has a gene mutation that puts her at higher risk for several cancers.
Source: Tara Kirk

Tara Kirk was 6 years old when her mother died of lung cancer.

Almost three decades later, at the age of 34, Kirk found out she had a gene mutation that increases her risk of developing a number of diseases, most notably colon and endometrial cancers.

"I was in denial that I could have had it," said Kirk, now 36 and living in Houston with her husband and son.

When people think of gene mutations, the breast cancer (BRCA) genes often come to mind. Actress Angelina Jolie famously laid out her decision to have a preventive double mastectomy after her BRCA1 diagnosis back in 2013.

The lifetime risk of breast cancer is increased by 20% to 49% for women with moderate-risk gene mutations and 50% or higher with those who have high-risk mutations, according to Susan G. Koman.

Angelina Jolie had a preventive double mastectomy in 2013, after discovering she had a BRCA mutation.
Samir Hussein | WireImage | Getty Images

In fact, researchers have associated mutations in specific genes with about 50 hereditary cancer syndromes, according to the National Cancer Institute.

For Kirk, it is the gene known as MSH6, one of several mutations that are classified as Lynch Syndrome.

While there was family history of cancer, she only got tested after her aunt was diagnosed with endometrial cancer. Kirk now believes her mother's cancer may have started elsewhere before traveling to the lungs.

Since her diagnosis, Kirk goes for annual screenings, including a colonoscopy, endometrial biopsy, ultrasound, and full body skin exam. She gets an upper endoscopy every other year and was told when she reaches 40, she should have her uterus and ovaries removed.

Fortunately, Kirk has insurance. About $3,500 a year comes out of her paycheck to pay for her employer-sponsored insurance and she spends an additional $2,000 a year out-of-pocket for her surveillance. It's a small price to pay for the chance to catch cancer early, she said.

"My very first colonoscopy they found a precancerous polyp, so knowledge saved my life," Kirk said.

When to get testing done

Not everyone is a candidate for genetic testing. In fact, only about 5% to 10% of all cancers are considered hereditary, although it varies by the specific cancer.

About one in 400 women have a BRAC1 or BRAC2 mutation, although those of Ashkenazi Jewish heritage have a higher risk: one in 40. Lynch syndrome affects approximately one in 270 people and causes about 3% to 5% of colon cancers and 2% to 3% of uterine cancers.

Tara Kirk and her mom in December 1988.
Source: Tara Kirk

To determine if you have a gene mutation, first gather your family history and see your doctor, said Susan Brown, senior director of education and support at Susan G. Komen.

If your health-care provider thinks you might have a hereditary mutation, you'll be referred to a genetic counselor, who may order a blood or saliva test.

"It's an easy test," Brown said. "The ramifications of the results can be a little more complicated.

"If you have a positive mutation, then you have to think about what you are going to do with that information."

Testing costs anywhere from a couple hundred dollars to several thousand dollars and may be covered by insurance. The multigene panel is pricey, since it surveys a number of genes.

If someone in your family has already been diagnosed with a specific mutation, you can be tested for that mutation alone, which is a lot cheaper. For those who don't have health insurance, many of the gene-testing companies have programs that bring the cost down to $250 to $300.

My very first colonoscopy they found a precancerous polyp, so knowledge saved my life.
Tara Kirk
Lynch Syndrome patient

Coverage of BRCA testing for women is required under the Affordable Care Act, although the fate of the law is uncertain. The U.S. Supreme Court is set to hear arguments on whether the ACA is constitutional after the election in November.

Coverage for other gene mutations is optional, but has grown in recent years, according to Lisa Schlager, vice president of public policy at the hereditary cancer advocacy organization Force, which stands for Facing Our Risk of Cancer Empowered.

"They do [cover testing] for the most part, but it can incur or involve out-of-pocket costs," she said.

Then there are direct-to-consumer companies like 23andMe and Ancestry. Generally, direct-to-consumer tests are not part of recommended clinical practice, according to the National Cancer Institute.

"If they are not done through a doctor in an approved lab, there is potential for errors," Komen's Brown explained.

Some tests may only check for a few mutations.

"You may make a decision and have an understanding of your risk based on incomplete information," she said.

More from Invest in You:
Yes, you can negotiate medical bills. Here's how to lower your costs
Actor Chadwick Boseman died without a will. Why you should have a plan
The big lesson Suze Orman learned from her recent health scare

For $179, AncestryHealth offers testing for genetic risks and says it can detect 80% or more of known DNA differences linked to certain cancers.

"AncestryHealth includes laboratory tests developed and performed by an independent CLIA-certified laboratory partner, and with oversight from an independent clinician network of board-certified physicians and genetic counselors," its website states.

Meanwhile, 23andMe's Health + Ancestry service includes testing for selected variants of BRCA1 and BRCA2.

"23andMe standards for accuracy are incredibly high," the company said in a statement. "Detailed analytical testing through the FDA review process showed that our Genetic Health Risk and Carrier Status reports meet accuracy thresholds of 99 percent or higher."

Costs of screening

If you are found to have a so-called "cancer-gene," you generally will start undergoing annual cancer screenings. You may also opt for preventive, or prophylactic, surgery — typically a mastectomy or hysterectomy.

The costs and amount of insurance coverage — if you have any — vary widely.

Heather Horton, 35, and her mother, 63-year-old Sue Williams, have had two vastly different experiences.

Heather Horton, L, and her mother, Sue Williams both have a gene mutation that is associated with a higher risk of several cancers, including colon.
Source: Sue Williams

The pair, who live in Portland, Oregon, both have the MLH1 mutation, another gene that falls under Lynch Syndrome.

Williams found out at the age of 54, after her brother was diagnosed with colon cancer in his 40s. She's had no issue with her coverage. She had a preventative hysterectomy and now undergoes regular colonoscopies and endoscopies, which cost her $20 after insurance. She pays $812 a month for her policy.

Horton, on the other hand, has become an expert at reading medical bills and understanding coding after spending a lot of time challenging charges.

Diagnosed at 28 years old, Horton gets the same screenings as her mom, plus ultrasounds, a blood test and an endometrial biopsy to monitor her uterus and ovaries. Over the years, her annual screening costs have run from about $800 to $2,500, with around $1,500 being the norm. Her monthly premium is about $520 for a family plan.

"One of the biggest challenges is [that] it's hard to really track or budget for, because I can't ever really estimate what the expenses are going to be," Horton said.

Fighting to bring down costs

Health insurers aren't required to cover cancer screenings, beyond what is mandated by the ACA, which is focused on the "average risk" population. That leads many to struggle to get coverage for earlier, more intensive screenings and risk-reducing surgeries, according to Force.

While insurance typically covers the surveillance, those who have high-deductible plans may still wind up with a hefty bill, said Force's Schlager.

"We are testing people but not empowering them with easy access, necessarily, to the follow-up care," she said.

Medicare doesn't cover preventive care, unless authorized by Congress. Right now, those over 50 years old can get screening colonoscopies covered and those over 40 can get screening mammograms — as well as a baseline between the ages of 35-39. However, anyone younger on Medicare, such as those with disabilities, won't be covered.

Medicare also doesn't cover breast MRIs, which doctors recommend for those with a high breast cancer risk, as well as preventive surgeries, Schlager said.

Our whole health system is focused on treatment. If we were to flip that and focus on prevention, we would probably save the system a lot of money long-term.
Lisa Schlager
vice president of public policy at Force

She's currently working on legislation with Sen. Lisa Murkowski, R-Alaska, and Rep. Debbie Wasserman Schultz, D-Florida, to amend the Medicare statute to broaden the preventive cancer screenings.

Medicaid coverage for screenings is more difficult to track, since it varies by state. All but three state programs cover BRCA testing and most cover testing for Lynch Syndrome. Less than a handful cover multigene panel testing, Schlager said. She recommends checking with your state's Medicaid office to find out what's available.

"Our whole health system is focused on treatment," Schlager said.

"If we were to flip that and focus on prevention, we would probably save the system a lot of money long-term. But we are just not there yet."

'Managing your destiny'

While there may be costs with cancer screenings, it is better than the alternative: not catching cancer early and paying for costly treatments.

"It is really managing your destiny as far as your health," said Susan Dallas, executive director of Lynch Syndrome International.

Her father passed away from pancreatic cancer when she was four years old. At 43, Dallas was diagnosed with colon cancer, and subsequently, Lynch Syndrome, which includes genes MLHL, MSH2, MSH6, PMS2, and EPCAM.

"If you don't know what you are dealing with, you can't possibly know what your potential cost could be down the road," Dallas said.

"It could save you thousands and thousands of dollars, not to mention the heartache, stress and loss of income because you end up with cancer."

In fact, a new report from the American Cancer Society Cancer Action Network titled "The Costs of Cancer" found that U.S. cancer patients spent $5.6 billion in out-of-pocket costs for cancer treatment in 2018. Those with ACA-compliant coverage paid between $5,000 out-of-pocket in a large employer plan to over $12,000 in an individual marketplace plan. Short-term limited duration plan patients paid $52,000.

Despite the frustrations she has encountered, Horton doesn't regret getting tested.

"Knowledge is power. We do have some of this within our control to stay on top of it," she said.

"There is some comfort in that, than just kind of waiting for some symptom to appear."

SIGN UP: Money 101 is an 8-week learning course to financial freedom, delivered weekly to your inbox.

CHECK OUT: I’ve made thousands of dollars a month in passive income for the past 5 years: Here’s how via Grow with Acorns+CNBC.

Disclosure: NBCUniversal and Comcast Ventures are investors in Acorns.

Let's block ads! (Why?)


"Here" - Google News
October 31, 2020 at 09:15PM
https://ift.tt/31ZsErL

Genetic testing can assess your risk of getting cancer. Here are the costs involved - CNBC
"Here" - Google News
https://ift.tt/39D7kKR
Shoes Man Tutorial
Pos News Update
Meme Update
Korean Entertainment News
Japan News Update

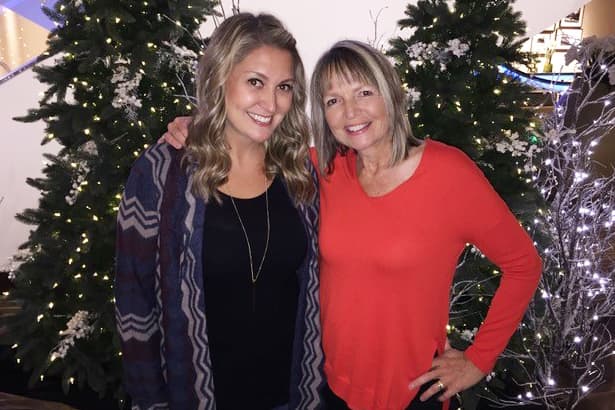
Here's how a Biden or Trump presidency would affect your personal finances - CNBC

Joe Biden, 2020 Democratic presidential nominee, right, and President Donald Trump during the presidential debate at Belmont University in Nashville, Tennessee, on Oct. 22, 2020.
Kevin Dietsch/UPI/Bloomberg via Getty Images

President Donald Trump and Joe Biden, his Democratic opponent in next week's election, have broadly diverging views on issues that would impact the personal finances of everyday Americans.  

It's no guarantee the candidates' ideas and proposals will eventually become law. Much hinges on the outcome of congressional races, for example.

But here are things to consider as voters head to the polls on Tuesday, on issues like taxes, Social Security, student loans and Medicare.

Taxes

The Trump campaign said it would "cut taxes to boost take-home pay and keep jobs in America." It offers scarce details on how this would be accomplished.

Experts believe the president would try to build on the Tax Cuts and Jobs Act, viewed as his signature legislative achievement during his first term.

The law, enacted in 2017, overhauled the tax code for individuals and businesses. It roughly doubled the standard deduction and limited some itemized deductions (like one for state and local taxes), among other things.

More from Personal Finance:
Here's a decade-by-decade guide to retirement planning
What a Trump or Biden plan will mean to student loan borrowers
Older workers are struggling to find jobs

On average, the law cut taxes for Americans across all income groups, according to a report published by the Joint Committee on Taxation last year.

The richest Americans pocketed most of the benefit. About 76% of the estimated $259 billion in taxpayers' total savings in 2019 went to those making more than $100,000 a year, according to the report.

However, the bill's tax cuts for individuals are temporary. They are set to expire after 2025 and revert back to prior law, effectively raising taxes.

The Trump administration would likely try to make these cuts permanent, tax experts said.

Doing so would raise after-tax income for all households, on average, delivering a 1.5% increase, according to the Urban-Brookings Tax Policy Center. The top 20% of Americans (making roughly $167,000) would get about two-thirds of the benefit.

Trump administration officials like economic advisor Larry Kudlow have also floated the idea of a tax cut for the middle class. Trump has also proposed cutting taxes on capital gains (the top tax rate of which is currently 20%).

Biden, who was vice president during the Obama administration, has proposed raising taxes for wealthy Americans. He would seek to reduce taxes for lower earners via mechanisms like a temporary expansion of the child tax credit.

The Biden campaign floated a top income-tax rate of 39.6% (up from 37%) for those earning more than $400,000. He would raise their payroll taxes, too.

The Biden plan would also limit the value of itemized deductions (write-offs for charitable donations and medical costs, for example) for wealthy households making more than $400,000.

Biden would also increase taxes on capital gains to 39.6% for those making more than $1 million a year — almost double the current rate.

"That's mega, mega significant. A lot of the ultra-high-net-worth people make a great deal of their income through investment income," said Jeffrey Levine, director of advanced planning at Buckingham Wealth Partners.

The top 20% (those making more than roughly $160,000) would be the only group to see a tax increase in 2022, according to the Tax Policy Center. Their tax liability would grow by 5%, or $14,700, in 2022.

Meanwhile, Biden would boost the child tax credit to $3,000 for kids 17 and younger, plus a $600 bonus for children under 6. (The credit is currently $2,000 for kids under 17.) Biden would also make it fully refundable, meaning taxpayers would get a refund even if they owe no tax. (Up to $1,400 is currently refundable for each child.)

The bottom 20% of earners would see after-tax income grow by more than 5%, or roughly $750, in 2022.

Some observers believe low and middle-income taxpayers could see negative indirect effects from Biden's proposal to increase the corporate tax rate, via increased prices for consumer goods or stagnating wages for employees.

Social Security

Biden's plan calls for boosting Social Security checks for individuals in many ways.

For example, his proposal would raise monthly payments for seniors who've been receiving benefits for at least 20 years, to protect against depleted retirement savings.

It would also set a minimum benefit — at least 125% of the poverty level — for those who've worked at least 30 years. Monthly survivor benefits for widows and widowers would grow by 20%.

Biden would also seek to improve Social Security's finances.

Earlier this year, the Social Security Administration projected the trust funds that help pay benefits would run out in 2035. At that time, around 79% of promised benefits would be payable, funded exclusively by payroll taxes.

The unemployment crisis caused by the Covid-19 pandemic has sped up that timeline by a few years, according to some estimates.  

Biden would impose Social Security payroll taxes on high earners to improve the program's solvency. Currently, workers pay 6.2% from wages, capped at wages up to $137,700 (which is indexed for inflation). Biden would also apply taxes to earnings over $400,000.  

Trump's campaign agenda says he would "protect Social Security." He's tweeted messages of support for Social Security on many occasions and said he would "save" the program.

The president signed an executive measure in August creating a Social Security payroll tax holiday, between Sept. 1 and Dec. 31.

It's a tax deferral, and workers would have to pay the tax back early next year. Businesses had to opt in. It only applied to workers making less than about $100,000 a year.

But Trump has floated forgiving that deferred tax.

"If I'm victorious on Nov. 3, I plan to forgive these taxes and make permanent cuts to the payroll tax," Trump said.

A permanent payroll tax cut could deplete the Social Security trust funds by mid-2023, according to Stephen Goss, Social Security's chief actuary.

Student loans

Biden has proposed forgiving $10,000 in student debt for all borrowers.

He would also forgive federal student debt tied to undergraduate tuition at public colleges and historically Black colleges and universities. That would apply to borrowers earning less than $125,000 a year.

Trump hasn't mentioned sweeping plans to forgive student loans. He's called for eliminating public-service loan forgiveness, which allows certain not-for-profit and government employees to have federal student loans canceled after a decade of on-time payments.

Biden would keep that program but make changes, instead forgiving $10,000 a year of undergraduate or graduate student debt for up to five years.

The Trump administration has allowed borrowers to pause monthly student loan payments without interest accrual during the Covid-19 pandemic. The U.S. Department of Education initially offered that moratorium in March, and the president signed an executive measure over the summer extending that pause through 2020.

It's unclear if that moratorium would be extended next year if Trump (or Biden) wins the election.

Medicare

Trump has taken some steps to ease costs for Medicare beneficiaries and has proposed some changes to the senior health program.

For example, the president has moved to reduce drug costs, by lifting "gag orders" on pharmacists that prohibited them from telling patients there was a cheaper option for their prescriptions, for example. He capped monthly insulin costs, effective next year, for some Medicare beneficiaries.

Trump also wants to send $200 payment cards to some individuals on Medicare to help pay for drugs, he said in a speech last month.

The Trump administration is supporting a lawsuit seeking to overturn the Affordable Care Act. That law, known as Obamacare, made some changes to Medicare. For example, it added certain free preventive benefits to Medicare and eliminated, over several years, a spike in out-of-pocket spending on prescription drugs that some beneficiaries faced.

Biden has proposed some changes to Medicare, too.

His plan would allow individuals to enroll in Medicare starting at age 60 instead of 65. The program would cover dental, vision and hearing, all of which are currently excluded.

Biden also wants to reduce the cost of prescription drugs for Medicare beneficiaries by, for example, allowing the government to negotiate those prices — which is currently prohibited by law. He would prohibit most drug prices from rising faster than inflation.

His campaign also supports the Affordable Care Act.

— CNBC reporters Lorie Konish, Darla Mercado, Annie Nova and Sarah O'Brien contributed to this story.

Let's block ads! (Why?)


"Here" - Google News
October 31, 2020 at 08:00PM
https://ift.tt/34OpHfP

Here's how a Biden or Trump presidency would affect your personal finances - CNBC
"Here" - Google News
https://ift.tt/39D7kKR
Shoes Man Tutorial
Pos News Update
Meme Update
Korean Entertainment News
Japan News Update
You can start a venture fund if you’re not rich; here’s how - TechCrunch

For years — decades, even — there was little question about whether you could become a venture capitalist if you weren’t comfortable financially. You couldn’t. The people and institutions that invest in venture funds want to know that fund managers have their own “skin in the game,” so they’ve long required a sizable check from the investor’s own pocket before jumping aboard. Think 2% to 3% of the fund’s total assets, which often equates to millions of dollars.

In fact, five years ago, I wrote that the real obstacle to becoming a venture capitalist has less to do with gender than with financial inequality. I focused then on women, who are paid less (especially Black and Hispanic women), and who possess less wealth. But the same is true of anyone of lesser means.

Thankfully, things are changing, with more ways to help aspiring VCs raise that initial capital commitment. None of these approaches can guarantee success in raising a fund, but they’re paths that other VCs have effectively used and are good to understand better.

First, find investors, i.e. limited partners, who are willing to take less than 2% or 3% and maybe even less than 1% of the overall fund size being targeted. You’ll likely find fewer investors as that “commit” shrinks. But for example Joanna Rupp, who runs the $1.1 billion private equity portfolio for the University of Chicago’s endowment, suggests that both she and other managers she knows are willing to be flexible based on the “specific situation of the GP.”

Says Rupp, “I think there are industry ‘norms,’ but we haven’t required a [general partner] commitment from younger GPs when we have felt that they don’t have the financial means.”

Bob Raynard, founder of the fund administration firm Standish Management, echoes the sentiment, saying that a smaller general partner commitment in exchange for special investor economics is also fairly common. “You might see a reduced management fee for the LP for helping them or reduced carry or both, and that has been done for years.”

Explore management fee offsets, which investors in venture funds often determine to be reasonable. These aren’t uncommon, says Michael Kim of Cendana Capital, a firm that has stakes in dozens of seed stage funds, because they also offer tax advantages (though the IRS has talked about doing away with these).

How do these work? Say your “commit” was $1 million over 10 years (the standard life of a fund). Instead of trying to come up with $1 million that you presumably don’t have, you can offset up to 80% of that, putting in $200,000 instead but reducing your management fees by that same amount over time so that it’s a wash and you’re still getting credit for the entire $1 million. You’re basically converting fee income into the investment you’re supposed to make.

Use your existing portfolio companies as collateral. Kim had at least two highly regarded managers launch a fund not with a “commit” but rather by bringing to the table ownership stakes in startups they’d funded as angel investors.

In both of these cases, it was a great deal for Kim, who says the companies were quickly marked up. For the fund managers’ part, it meant not having to put more of their own money into the funds.

Make a deal with wealthier friends if you can. When Kim launched his fund of funds to invest in venture managers after working for years as a VC himself, he raised $1 million in working capital from six friends to get it off the ground. The money gave Kim, who had a mortgage at the time and young children, enough runway for two years. Obviously, your friends have to be willing to gamble on you, but sweeteners certainly help, too. In Kim’s case, he gave his friends a percentage of Cendana’s economics in perpetuity.

Get a bank loan. Rupp said she would be uncomfortable if a GP funded his or her commit through a bank loan for several reasons. There’s no guarantee a fund manager will make money from a fund, a loan adds risk on top of risk, and should a manager need liquidity related to that loan, he or she might sell a strongly performing position too early.

That said, loans aren’t uncommon, says Raynard. He says banks with venture capital relationships like Silicon Valley Bank and First Republic are typically happy to lend a fund manager a line of credit to help him or her make capital calls, though he says it does depend on who else is involved with the fund. “As long as it’s a diverse group of LPs,” the banks are comfortable moving forward in exchange for winning over a new fund’s business, he suggests.

Consider the merits of so-called front loading. This is a technique with which “more creative LPs can sometimes get comfortable,” says Kim. It’s also how investor Chris Sacca, now a billionaire, got started when he first turned to fund management. How does it work? Some beginning managers blend their annual management fee of 2.5% of assets under management and pay themselves a higher percentage  — say 5% for each of its first three years — until by the end of the fund’s life, the manager is receiving no management fee at all.

That could mean no income if you aren’t yet seeing profits from your investments. But presumably — especially given pacing in recent years — you, the general partner, have raised another fund by the time that happens so have resources coming in from a second fund.

These are just a few of the ways to get started. There are other paths to take, too, notes Lo Toney of Plexo Capital — which, like Cendana Capital — has stakes in many venture funds. One of these is to use a self-directed IRA to finance that GP commit. Another is to sell a portion of the management company or sell a greater percentage of your carry and use those proceeds to pay your commit. (VCs Charles Hudson of Precursor Ventures and Eva Ho of Fika Ventures avoided that path and suggested that first-time managers do the same if they can.)

Either way, suggests Toney, a former partner with Alphabet’s venture arm, GV, it’s important to keep in mind that there’s no one right way to raise a fund — and no disadvantage in using these strategies. Said Toney via email this week: “I have not seen any data on the front end of a VC’s career that wealth indicates future success.”

Let's block ads! (Why?)


"Here" - Google News
October 29, 2020 at 02:00PM
https://ift.tt/2JrawRv

You can start a venture fund if you’re not rich; here’s how - TechCrunch
"Here" - Google News
https://ift.tt/39D7kKR
Shoes Man Tutorial
Pos News Update
Meme Update
Korean Entertainment News
Japan News Update
Search

Featured Post

A New Cafe, Cocktail Bar, Sports Pub, and Pickleball Destination Is Opening in Far South Austin - Eater Austin

takanadalagi.blogspot.com Two new sibling bars are opening in far south Austin sometime this year. There’s cafe and cocktail bar Drifters S...

Postingan Populer